Wind or flood decides who pays, and day one decides that
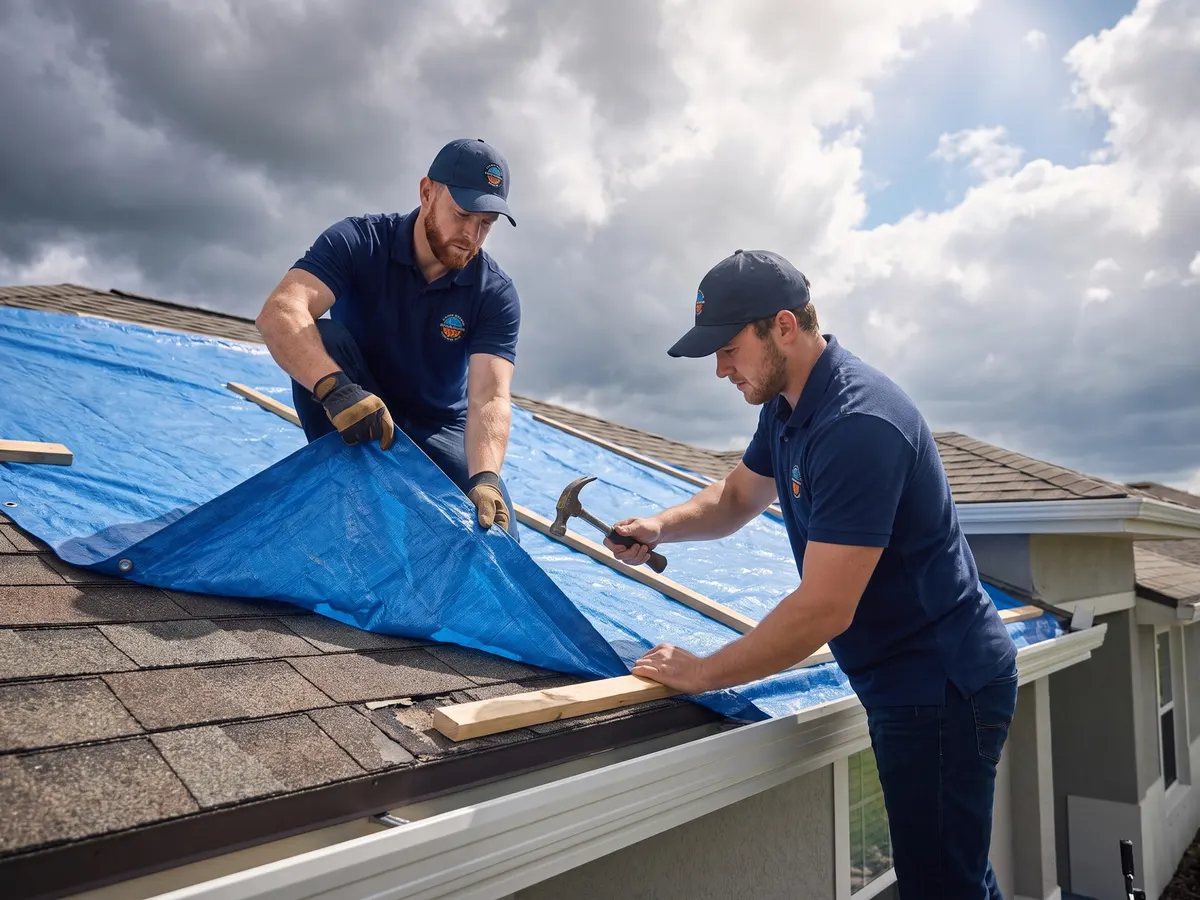
The same wet drywall can be two different claims. Under federal rules, flood includes the overflow of inland or tidal waters, so storm surge is a flood loss and belongs to a flood policy, not the homeowners policy. Florida homeowners policies exclude flood outright. What they do cover, under Florida Statute 627.4025, is interior damage from rain, hail, sand or dust — but only where the direct force of the windstorm first damaged the building and created the opening the rain came through. Roof off first, then rain: wind claim. Water in at the slab: flood claim.
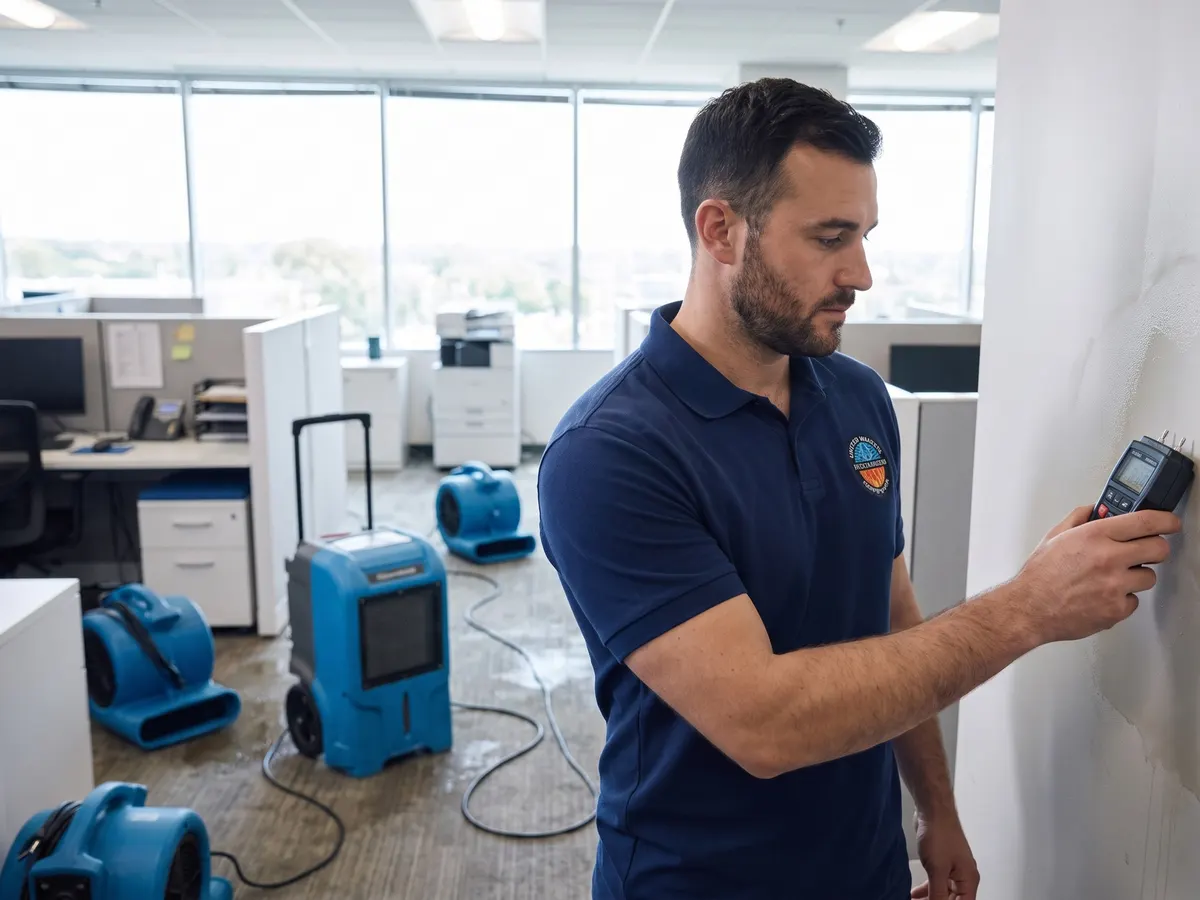
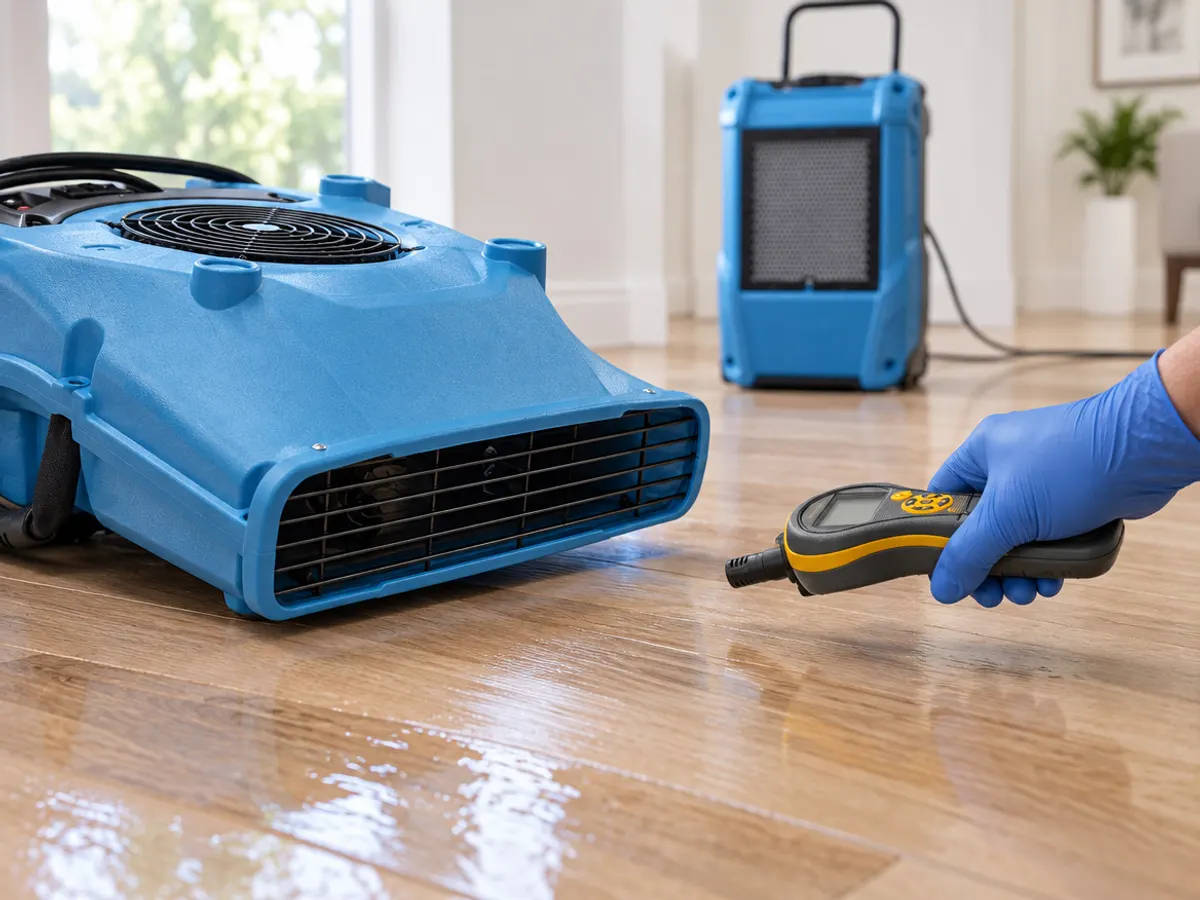
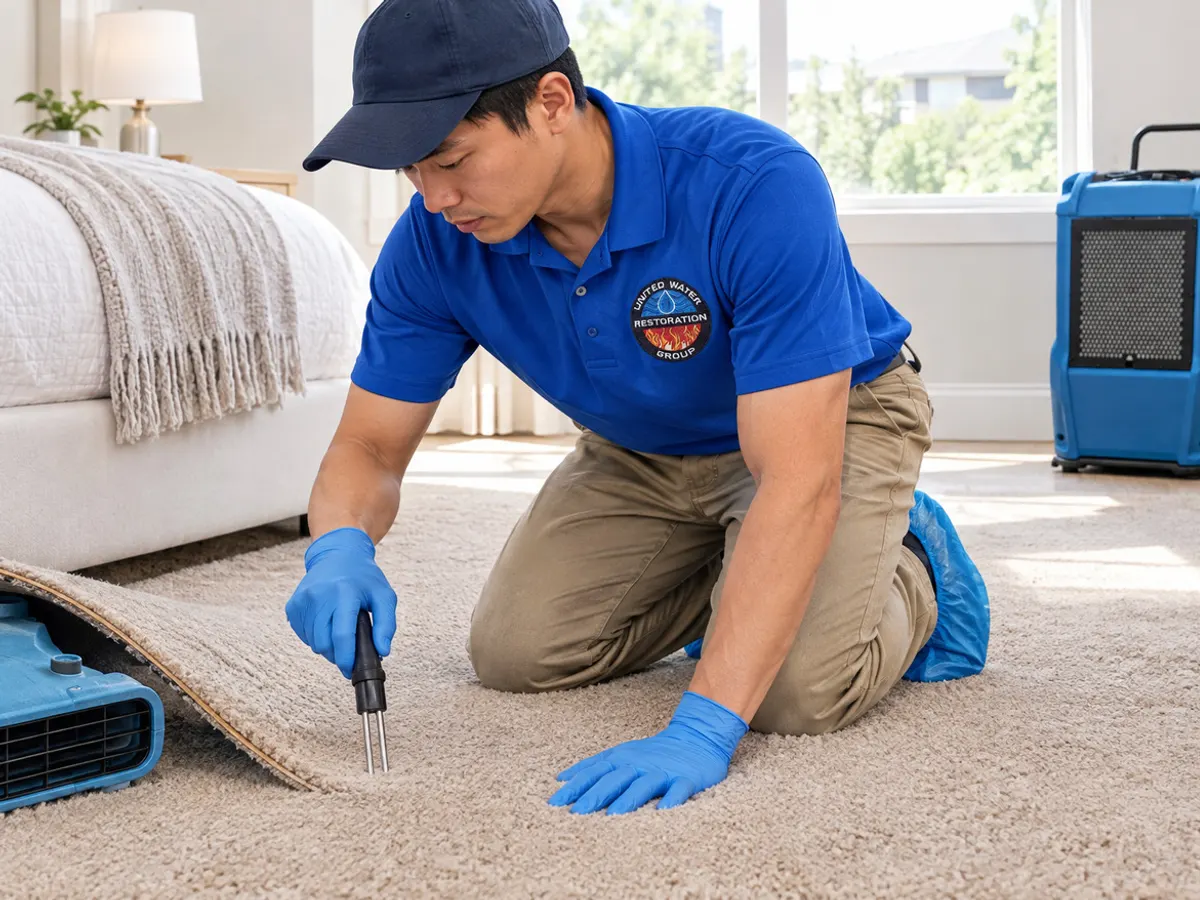
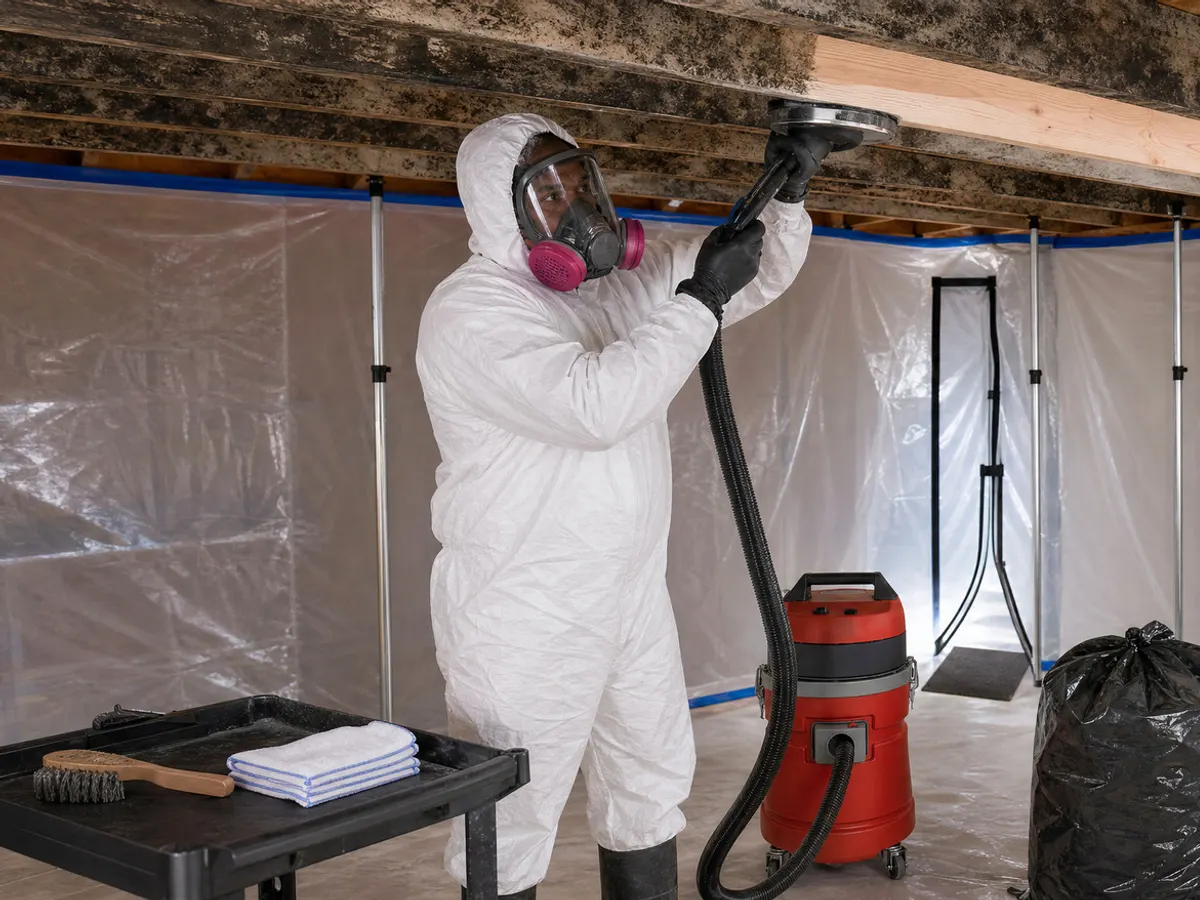
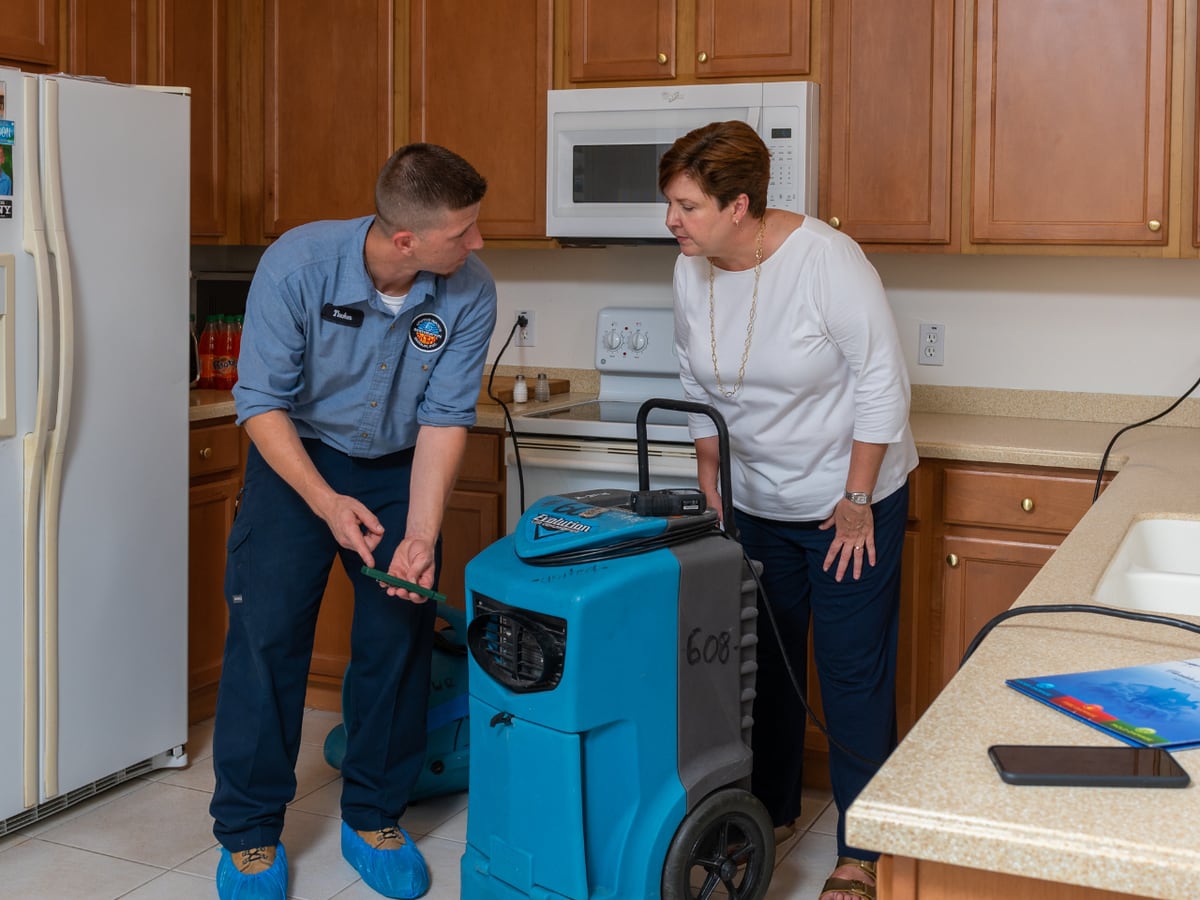
That distinction is decided by what gets documented on day one, which is why we photograph the water line on the walls, the entry path, the soffit or roof breach, and the debris line outside before anything is torn out. We write moisture readings by room and date. If we are wrong about the source we want the record to show it, not our opinion.
A few other things worth knowing before you call anyone. Florida hurricane deductibles are a percentage of the dwelling limit, not the loss: five percent on a $400,000 limit is $20,000 out of pocket. That deductible applies once per calendar year per insurer group, not once per storm, and when it applies no other deductible stacks on top. A claim is barred unless reported within one year of the date of loss, and for a hurricane the clock starts at landfall, not the day you noticed the ceiling. Supplemental claims get eighteen months.
We will not tell you what your carrier will pay, and since January 1, 2023 Florida policyholders cannot assign post-loss benefits to a contractor. You remain the claimant. We document the loss, do the work, and bill you — and we will talk to your adjuster with you on the phone.